Thursday, 21 April 2016

I'm selling HPH Trust (NS8U.SI)


Following HPH Trust's result announcement, I've finally decided to part ways with this stocks. In many posts here, here and notably here, I had voiced concerns about the sustainability of the dividends payout and the effect of China's slowdown. Unfortunately, due to procrastination and the time taken up by school work, I was unable to followup with a review of HPH Trust. On top of the 26% drop in underlying NPAT attributed to shareholders, this announcement also came with a very jarring note which stated it is:

"...repaying a minimum of HK$1 billion of debt annually beginning in 2017"


Dividend Issue

Woah, hold it right there. The amount is no small sum at all. Taking 2015's distribution amount which comes up to HK$2996.6 million or 34.40 HK cents per share, repaying HK$1 billion per year will cut this distribution amount to 22.92 HK cents or 33.3% drop!! Now, this is just purely assuming that the repayment solely comes from the hand dipping into the distribution income. Some might be taken from its existing cash pile...?

But take a look at Total Consolidated Cash at 31 March 2016: $5,995.6

It's not much at all. Keep in mind that HPH Trust need $1 billion per year for 5 years, not to mention servicing of short term debt. Another consideration is the dropping NPAT attributable to shareholders (no time to consolidate data, sorry!), which will eventually lead to decreased DPU. 2015's yield was exactly 8.0% based on my purchased price of US$0.68. Given that the first half of the dividend had already dropped 14%, the forecasted yield based on my purchase price is around 6.8% for this year. Conservatively taking out another 20% drop in DPU because of debt repayment, the dividend yield in 2017 will be just 5.5%!!. I had mentioned that my comfortable level was actually 6.5% and this violated my reason to buy/hold HPH Trust.

Will it fit into my portfolio?

5.5% is a decent dividend for any stocks and the fact that STI is one of the top dividend yield index in the region may just be because of HPH Trust! However, does it justify a place in my portfolio after all? I'll be using a concept I've learnt in my FIN3101 class (hello Prof Ruth!) - the Modern Portfolio Theory. 
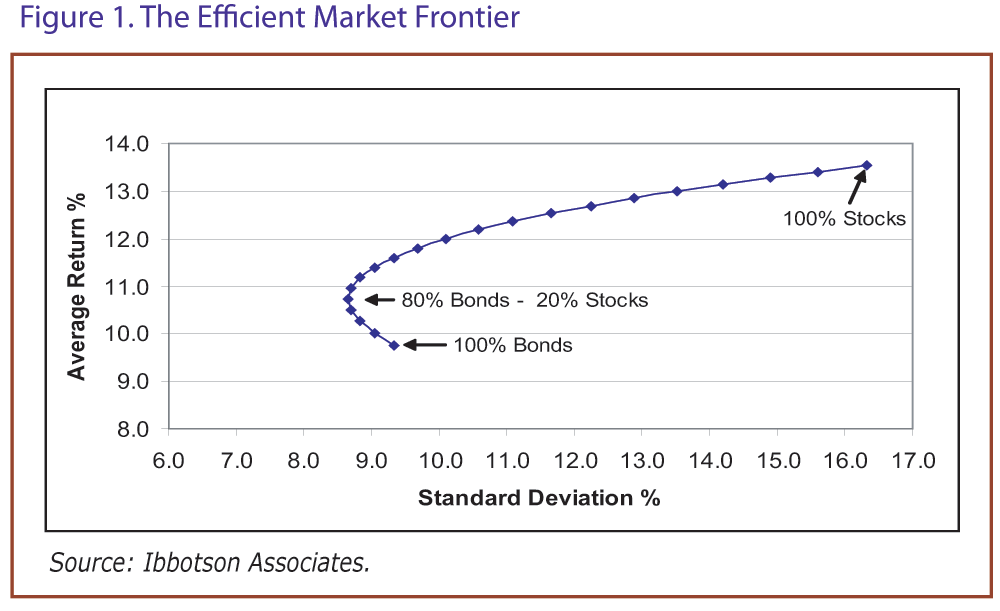
I'm not going to explain in details about this concept, but in general it is about using diversification to bring the risk of a portfolio down to your acceptable level and get the best expected returns, through varying the weights of your portfolio components. 

To cut to the chase, I had actually found that by removing HPH Trust from my portfolio, the standard deviation or risk of the portfolio did not change and it was actually accompanied by a marked increased in expected mean return of the portfolio. This essentially signified that HPH Trust did not contribute to my portfolio in terms of risk and was actually detrimental in terms of expected returns. 

This was actually my first time using this method to analyze my portfolio and I was excited to find out about this fact! The photo below shows my calculation and any guru that may come by this humble blog can double check my workings. 


Seeing that future dividends are going to be cut and finding out that HPH Trust is useful in my portfolio, I have decided to sell this stock. Queued at US$0.465 all day to no avail, I will continue to try tomorrow or at least in the immediate term. 

Monday, 4 April 2016

My Stock Holdings (March 2016)

After a long wait, I can finally sit down and count my gains for the month of March! With the Singapore stock market in the doldrums for the first two months, there were finally some rebound even though I did not enter anything prior to it. However, as I also did not let go of any stock, it meant my portfolio clawed back some gains.

This also highlighted how investing is actually advantageous to constant trading. According to this article, missing just the best ten days of S&P in the period between 1993-2013 will cost the investor a 3.8% drop in annualized returns. While many will argue that trading is better as one can let go of stocks at the highest and buyback at a lower point, I can assuredly say that I neither have the skills nor the time. Hence, as a student and eventually a working adult, passive investing will still be the way to go.

On the matter of dividends, I received a total of $227.42 for the month of March. This amount was disbursed from HPH Trust, SingPost and Karin Tech. Hence for the first three months, the total dividends received comes up to $261.57, a little over a quarter of my dividend goal this year.

Also, I had bought GLP on 31 Mar 2016 for a cost of $1.955. A little high, but through the average of valuation methods which I may subsequently write about,  the fair value price of GLP I came up with was actually $2.42. Coupled with GIC being the majority shareholder, I feel that there is some merit to the purchase of GLP. With the addition of GLP, the breakdown of my portfolio is shown below. Let's hope 2016 is a good year for all in the stock market =)


Tuesday, 1 March 2016

My Stock Holdings (February 2016)

Whew, busy month with Design Project, FYP Presentation, projects, tutorials, midterms. For record sake's, I have come online to record this short entry of my stock holdings in February. Whilst the market condition is still bad, there is a restoration of stability and hence marginal growth.

In the month of February, Keppel Reit has declared a dividend of $0.0168 per share. I chose to reinvest this dividend through the DRP. While filling up the form, I realised that I can allocate the shares I own to either 1) Receive the cash dividend OR 2) Receive new shares. Knowing this, I can allocate some of my share to receive cash dividend while still receiving the same number of new shares. This is possible because there can be no shares lower than 1 and is thus rounded down. Might as well use this spare shares to receive the cash dividend! The amount is not huge, but I hate to give away free money.

Therefore, the first dividend I received this year will be $34.15. The start to my $1000 dividend aim for this year. Below is my stock holdings at the end of February. Noticeably, HPH Trust has fallen in overall value to stand below Keppel Reit.


PS: I finally found a job!

Friday, 5 February 2016

My Stock Holdings (January 2016)

Below is my portfolio distribution for the first month of 2016. Here's to a better investing future for the rest of the year! 


From the start of this year till end of January, the main movement was me selling Bank of Ireland in favor of Karin Tech. The sale of Bank of Ireland was triggered by the disappointing lack of positive push to the stock. Though the economy for Ireland and Europe had been improving for a while now, with stable dividend on the way, it had not translated into positive movement for the stock. The premise of me buying Bank of Ireland back in 2014 was based on the improving economy in Ireland as well as the improving of the bank's balance sheet. Both events happened without any significant price increase. Hence by referring to my buying motivation, I had realised holding the stock by this point, meaningless. This also serves as a good lesson for readers out there that when buying stocks, remember to write down your reasons for writing it. Periodically review it to see that the reasons are still valid and if the reasons are not valid anymore, consider selling it. 

Following the previous post about Karin Tech, I have decided to add the stock into my portfolio for the strength of management, resilient earning power, advantageous foreign exchange and good dividend. However, from the announcement from the company on Wednesday, I might have misjudged the strength of the business itself. Profits from Karin Tech plunged approximately 80% due to softening consumer electronics product. I had reservations about that section of business due to the low economic moat, but I did not expect it to drop so much. Nevertheless, a dividend of 0.05 HKD translate to a half year dividend yield of 3%. This is sufficient for me to consider holding it for longer periods of time. A warning to any investors though, the stock had fallen below the 3-year low of $0.285. Hence, a short term investor may have problem holding it. 

HPH Trust has also announced their results recently with a drop of dividend. A constant worry of mine is the huge debt of HPH Trust. Though HPH Trust has good dividends in the past years, the stock price drops along with the dividend and I wonder if the dividends/business is sustainable in the long year. I will be reviewing this stock with more spare time. 

SingPost announced marginal growth in profit despite higher revenue. It is really frustrating that profit does not grow proportionally with revenue. Logistics can be a lower margin business. However, having waited over 2 years for profit catch up, it does not appear to be happening. Management guided that "transformation" is finalizing and it is time to reap its fruits of labor. With the departure of Wolfgang Baier, I really wonder how the company is going to fare in the future. If not for my wonderful entry price, I may have sold this stock already. Perhaps I sound salty, but the downgrade from OCBC is infuriating. Within a quarter, the bank has conveniently slashed $0.82 off the target price of SingPost. While details has been lacking for the justification of the new TP, I find it unbelievable that the cut is so much within a quarter. Makes me wonder do the research house just see.... "heyyyy, the current trades so far from our TP. I think it's time to cut it nearer to current price to stay relevant." Also, I don't see eye to eye with people stating that dividend has increased from 1.25 cents to 1.5 cents. This is because it had been declared by SingPost since 1 year ago and should have been factored into stock price long ago. Don't mislead potential investors.


-End of whinings-

With the removal of Bank of Ireland, my portfolio has transformed into a full dividend machine and I hope I can meet my dividend target this year. The Year of Monkey should be good to people born in the Year of Goat and I hope it is true! So Happy Chinese New Year all! Have a prosperous year ahead!!

Monday, 18 January 2016

Karin Technology Holdings (K29.SI)

http://www.karingroup.com/eng/images/global/home_logo.gif

Business

Karin Tech is a leading electronic and industrial components distributor and providor of IT solutions, as well as outsourcing service provider in Hong Kong and China. In 2011, Karin included retail arm to its operations, opening four In-Smart stores in Hong Kong. . Though the business sounds unappealing, the surprising fact is this:

Since 1977, the company had always been in profit!

The company did not enjoy continuous EPS growth as its earnings were affected in the wake of 2008 GFC and in 2014. However, the fact that the board was able to maintain profitability despite many economic downturns is indeed commendable. The company also has a substantial economic moat due to its very diversified business. Listed on its Products & Services, Karin Tech looks like a semiconductor company and a IT solutions provider. Throw in the retail arm, Karin Tech has a hand in every section of the technology sector. The business not as exciting as companies like Apple or even Foxconn, but I particularly like companies that no one pays attention to.

Dividend

Business aside, let's look at the company's past dividends. The most attractive part of Karin Tech is actually a dividend yield that matches REITs and Business Trusts. Below is the dividend yield for 2013, 2014 and 2015. 

Year Dividend (S$) Closing Price for Year Dividend Yield
2013 0.0264 $0.33 8.00%
2014 0.0228 $0.30 7.60%
2015 0.0313 $0.31 10.10%


As you can see, the dividend yield for Karin Tech is substantial and comparable, if not better than many dividend stocks out there. Another point to note is the closing price for each year. Notice that the price is not volatile at all. Hence if you would are okay about not chasing capital gains but settle for dividends, Karin Tech is indeed very appealing. 

As with all dividend, one have to check how sustainable the dividend policy is. Below is the graph of how dividend payout correlates against EPS of the company. From the graph, you can see that management had discipline in keep dividend payout in line with EPS. Dividend payout average at approximately 50% throughout the years. Therefore, the dividends are indeed sustainable and payout are strictly adhered to by the management.


Valuation Metrics

From Yahoo website, the P/E of Karin Tech currently stands at 8.16. For a company that is relatively low profile with not as "attractive" business, I would say that the P/E is reasonable but leaves room for upside. For P/B, I referred to POEMS Stock Analytics and yield a figure of 0.56. Both P/E and P/B indicated that the margin of safety is relatively large. A downside I identified is actually how the stock rolls with the dividend payout. For example in 2010, when 8.2 HK cents of dividend was paid, the year end price was $0.22 - 6.5% yield (ignoring currency). Market historically had priced this stock to yield high dividend, which means that upside might be limited as well.

A catalyst that warrants a share price increase is the fact that HKD, by proxy of USD had already increased against SGD. Since HKD is pegged to USD, the stronger USD meant that the earnings of the company will be higher. Also, dividends paid out by the company is denominated in HKD, which might potentially mean higher payout. Most of the time, I feel that the market do not pay much attention to currency exchange (maybe because the companies always strip of forex gain/loss anyway) but in this case where dividend is transacted in HKD, perhaps this Karin Tech might be worth a look.

I'm none the wiser about the general strength of the industry. However, judging from the slowing economy in China, perhaps Karin Tech might be negatively affected by it. But, it is definitely worthwhile to note that the strength of management will make me comfortable holding the stock long-term and ride out downturns with them, all the while collecting the dividends they give out.

Valuation

The historic EPS growth between 2004 and 2015 was 5.87% annually. Projecting CAGR forward, the EPS in 2017 will hit 0.3295 HK cents or approximately $0.06. Applying the same P/E of 8, the simple projected price of Karin in 2017 should be around $0.48 (share increase in excess of 50%).

The current value arrived using Gordon Growth Model is looks even more monsterish. From Reuters, the beta of Karin Tech is 0.21. Re-using the risk-free rate and market's rate of return from previous post, the required rate of return or discount rate amounts to 3.465%. In 2005, the dividend was 6 HK cents while in 2015, it was 17.6 HK cents. Taking into account that 2015 was a record profit year, I will slightly adjust the "ending" dividend to 15 HK cents. Thus in the span of 10 years, the dividend growth of Karin was 9.6%. If you realise, the discount rate is actually lower than dividend growth and hence lead to a negative stock price (technically not possible).

Hence, an alternative will be to lower expectations and change using Constant Dividend Growth to valuate the company. Let's lower expectations even further and assumed that the upcoming year's dividend is 10 HK cents (44% drop). Using the formula, the current stock price for Karin Tech should be HK$2.89 or S$0.52.

Conclusion

 From the valuation section, you can see how horrifyingly undervalued Karin Tech is. However, there are some issues to consider. One would be the continuation of business and dividend. Will dividend continued indefinitely? Is the survival of business a cause of concern? Perhaps the growth of the entire business will be in jeopardy in the near future due to slowing economy of China.

However:

  1. P/E and P/B are very low, similar to unfavoured industry. Given that it is a high dividend yield stock, I think it should command higher valuation
  2. Business had always been profitable. Good economic moat
  3. The company had been faithfully declaring dividend for the past 10 years
  4. Recent hike in US$ (of which HK$ is pegged to) against S$, translating to higher dividend

Given all these reasons, I think Karin is  a safe bet and have taken a small position. 

Saturday, 16 January 2016

2015 Investing Report Card

In my previous post, I mentioned that my "financial year" ends on 13 January 2016, since it was the date I started tracking 2015 investment returns. Now that the day had past and I finally handed in my Final Year Project report, I can finally sit down to type out this post!

2015 Annual Return: -10.412% (for year ended 13 Jan 2016, using Excel's XIRR function)

With a portfolio that is down more than 10%, it was definitely not a good year for me. The consolation is that using the same calculation metric, the 2015 return for STI ETF was actually -16.099%. 

Hence comparing my portfolio against the STI index, I had technically "beat the market" for the year of 2015. Since many books had mentioned professional fund managers have trouble beating the market, I take pride that I had achieved the feat in 2015. It was a tough year especially with China's economy not doing well and oil price being so depressed. As a graduating student, I can sense that Singapore's economy is not doing well at all. This is so because of the tight job market available for me. My wish for 2016 is for me to get a job and start my own monthly investment plan, putting a part of my salary in STI ETF. I do not mind that the stock market tanks because over the long term, buying in a bear market inflates your returns. Buy when others are fearful!!

Note: Recently, someone introduced me to Holding Period Return as a way to calculate portfolio return, instead of XIRR. I am still not sure which is more accurate. Hence for 2016, I will keep track of my investments using both methods and observe how far they deviate from each other.


Here are some of the fun facts about my portfolio performance in 2015:

  • Dividends are probably the reason why my portfolio managed to outperform STI ETF - receiving $863.19. 
  • Dividend yield for portfolio is 4.80%, Excluding stocks that did not give dividend, the yield goes up to 6.17%.
  • I'm not a perfect investor. I trade sometimes (or technically, gamble). With 5 sets of Buy-Sell trades, I made a loss of $438.45. Portfolio return would have been better if my hand had not got itchy.
  • Narrowly missed losing a whole lot more if I did not sell Ezra in time. Ezra closed at $0.0900 that same day.

  • 2015 was also a bad year because none of the stocks I bought for investment purposes finished the green. Stocks included K-Reit, k1 Ventures and Straco. The only positive investment which I sold off was Apple Inc, which I bought in 2014 and sold in March 2015. 

2015 was an overall bad year while 2016 remains uncertain and volatile. Within the first 2 weeks, STI had already dropped 8.46% and the future of oil rigs giants KepCorp and SembCorp look threatened. Having started investing in 2011, I have not met any bear market or recession. No one can claim to be "experienced" if he/she have not gone through a financial crisis. Hence I am actually excited for 2016! Bull or bear, I will still be in the market, seeking my private returns. 

Sunday, 3 January 2016

My Stock Holdings (December) & Happy New Year 2016!


2015 stock market closed without a bang, neither a plunge. But it's undoubtedly a bad fairly lousy year. Starting the year at 3370.59 and ending it at 2893.19, STI dropped 14.16% excluding dividends. Oil price had bottomed to a 11-year low and does not seem to be recovering any time soon. Relevant companies in the oil industries had taken a hit, in particular Keppel Corp and SembCorp.

In my own portfolio, SingPost dropped almost 8% partly because of its CEO's departure and corporate governance problems. In my previous posts on SingPost, I mentioned how much I admired Wolfgang Baier's leadership in transforming SingPost. Now that he is actually gone, a closer watch on SingPost's performance in e-Commerce will be warranted.

Consistently under-performing stocks in my portfolio will also be reviewed soon. (once I submit my FYP report) These stocks actually include Bank of Ireland (BKIR) and HPH Trust. Since buying them almost 2 years back, they had returned almost zero returns. In fact, accounting for inflation and further brokerage fees and foreign custody fees, they were probably negative returns. In the long term, I am pessimistic about HPH Trust since there is little impetus for the share price. Management guidance of allowing dividend payout to follow cash flow should further compress dividend yield. For Bank of Ireland, there should be a slow recovery of its business towards declaring dividend late 2016 or early 2017. However, holding BKIR incurs foreign custody fee at POEMS and it is very vexing. Given the time, I would love to assess whether switching out BKIR and HPH Trust are preferable. (using capital budgeting concepts I learnt in FIN2004X!)

Rounding the "My Stock Holdings" posts for the year, below is the distribution of my portfolio at the end of December.


I received $150 from k1 Ventures through its capital reduction exercise. Adding it all up for the year, I had received $863.19 in 2015!

Since I will be working in mid-2016, I shall aim to achieve $1000 worth of dividend in 2016! This means putting some portion of salary into the stock market, maybe through dollar-cost averaging of STI ETF! Lastly, I shall write another post regarding my investing performance for 2015 as I started my records on 13 January of last year. Included will be breakdown of my Buys and Sells etc. Since I have not sat down to look at my records, writing that post is equally exciting for me!

Once again, Happy New Year and here's wishing everyone out there a prosperous and joyous year ahead! HUAT AH!